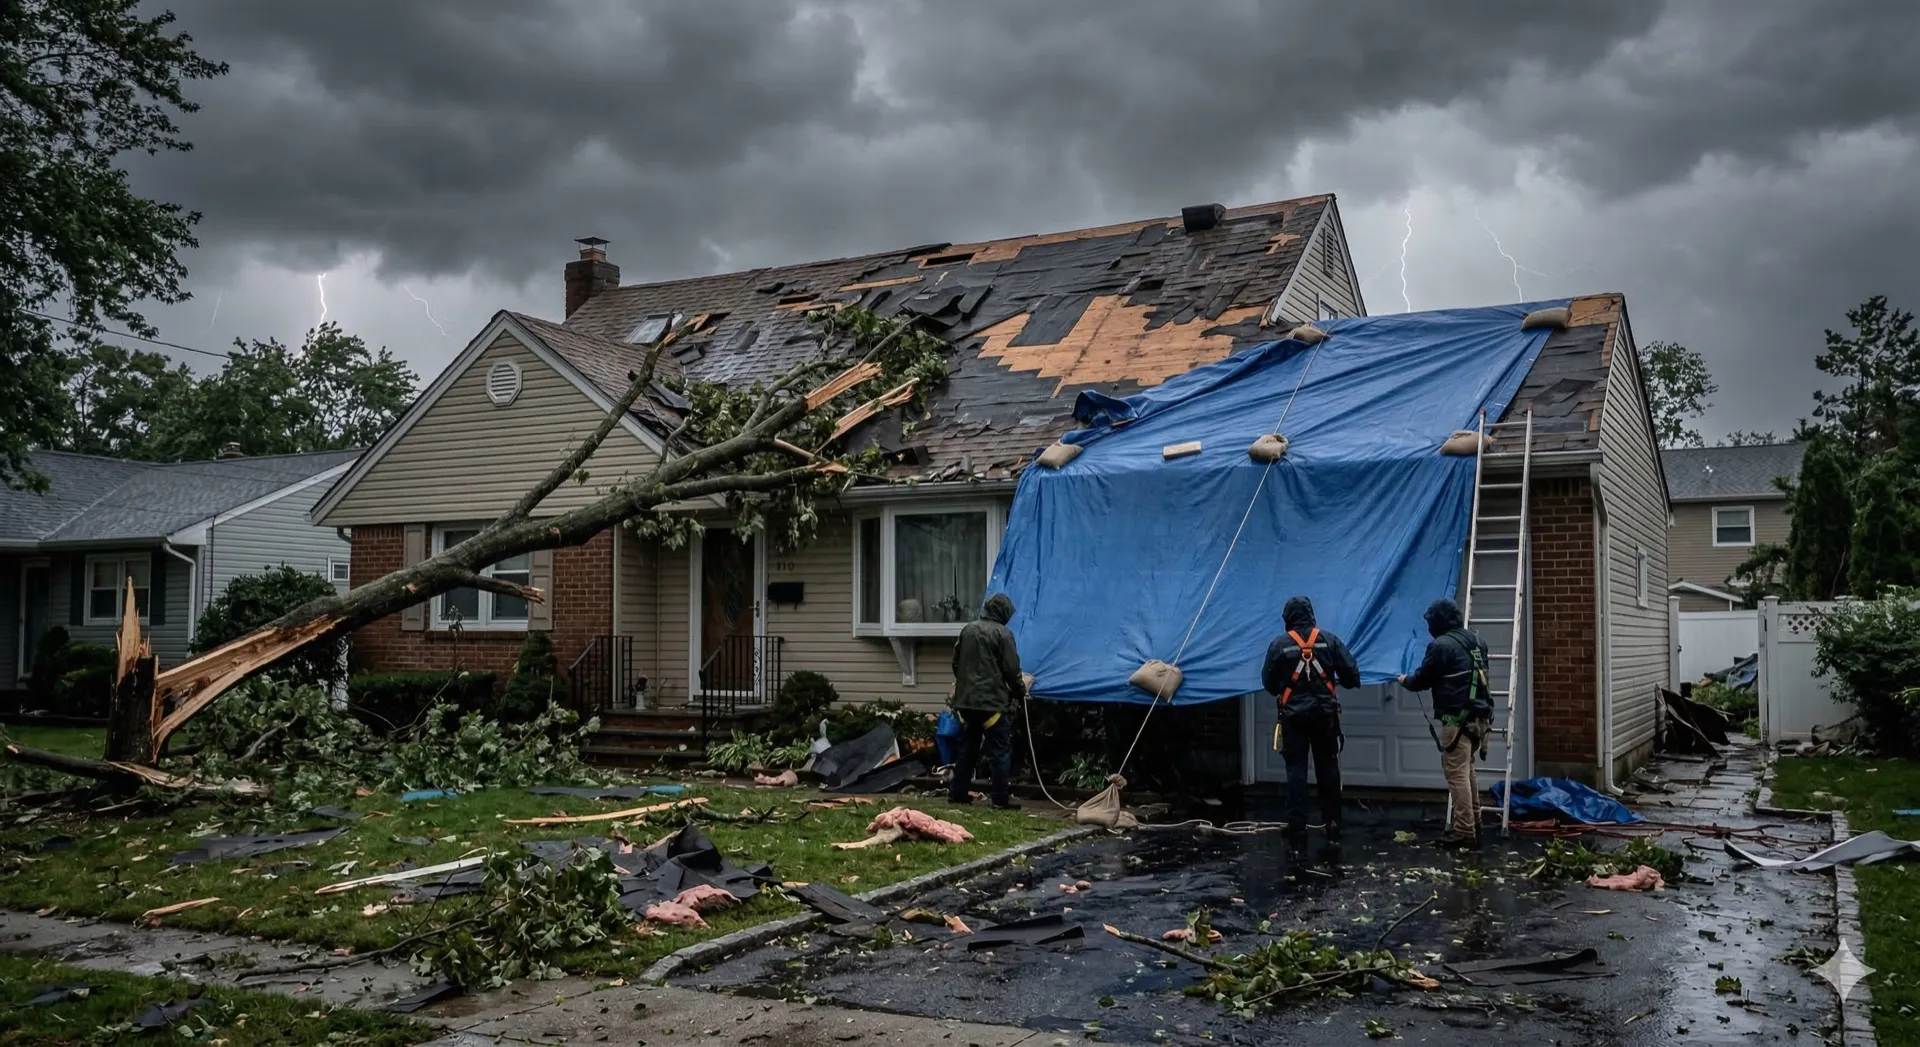
Alec's Construction handles hurricane and storm damage in Holbrook, Suffolk County — fallen trees, flooding and water damage, roofs and siding torn open, the cleanup and the rebuild — as one job from the first tarp to the finished repair, working out of the yard in East Patchogue. If the roof is open, a tree is on the house or there is water inside, call or text (631) 312-7441 rather than fill in the form, and tell us what you are looking at.
What a Hurricane Does in Holbrook
Holbrook is inland, split between the Town of Islip and the Town of Brookhaven, and a hurricane here is a wind and tree event on a big scale because the hamlet is one of the most heavily treed of the 1960s–70s developments in central Suffolk. Mature oaks and pines planted or left when the ranches and splits went in are now sixty years taller and standing over the roofs. The oaks shed heavy limbs; the pines come over whole. The houses themselves are one-storey or low-profile splits with a lot of roof and not much height, so the roof takes the tree and the roof takes the wind — ridge caps, the first courses at the eave, and the flashing at the low-slope garage roof are what we find lifted after a storm.
Inland: Wind, Rain and Pitch Pine
There is no tidal water here, so a hurricane is what the wind and the trees do. The pitch pine that covers the sandy ground has a shallow root plate and a tall thin trunk, and after a day of rain has loosened the soil it comes over whole — roots and all — onto the low roof of the garage wing, the deck, the car and the service drop. The oaks shed heavy limbs instead. The 1960s–80s splits and hi-ranches take the wind on the low-slope roof over the lower wing, where the shingles have the least overlap, and on the gable ends, where the wall is tallest. Then the rain gets in where the shingles lifted and shows up on the ceiling below.
What We Handle After a Storm
- Fallen or damaged trees — the tree on the roof, the limb through the porch, the leaner against the wall. Structural check first, then removal in the right order, then the repair.
- Flooding and water damage — surge, rain that came in through the roof, the basement that filled. Wet material out, real drying equipment in, moisture measured before anything is closed.
- Interior and exterior storm damage — roofing, siding, windows, soffits, gutters, ceilings, walls, floors and insulation.
- Storm cleanup and debris removal — cut, haul and clear, so the repair crew can get to the house.
- Repairs to damaged areas — from a tarp on the first day to the finished rebuild, one crew, one scope, one point of contact.
The Order of Work
- Make it safe. Nobody goes under a tree on a roof or into a room with a sagging ceiling until it has been looked at. Downed lines are the utility's, and they get called first.
- Photograph everything as found. Before a limb is cut or a wet carpet is pulled. This is what both claims rest on.
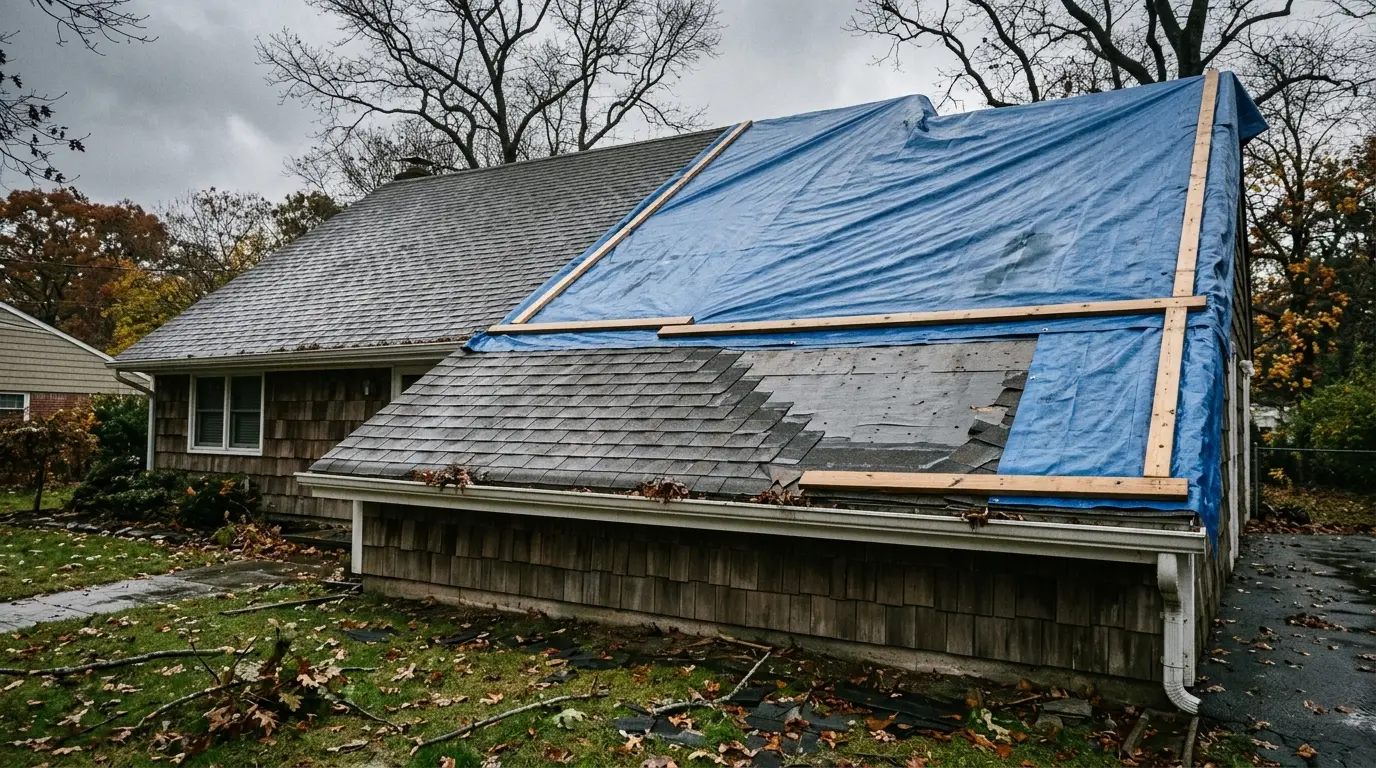
- Stop the water. Tarp the roof, board the openings, pump and pull the wet material that will grow mould if it stays.
- Dry and document. Drying equipment in, moisture readings taken and kept.
- Write the scope line by line with the photographs attached, storm damage kept separate from wear, wind damage kept separate from flood damage.
- Rebuild to the agreed scope, and correct what let the storm in so it does not repeat.
Homeowners Policy, Flood Policy and the Hurricane Deductible
Wind damage, and the rain that came in through it, is a homeowners claim. A tree on the house is a homeowners claim, and most policies pay something toward removing that tree, up to a limit that varies by policy. Water that rose — from the bay, a canal, a creek or a river — is a flood claim under a separate flood policy, whether National Flood Insurance Program or private, and the homeowners policy generally excludes it. Many coastal New York policies also carry a hurricane deductible that is a percentage of the dwelling coverage rather than a flat figure, and it applies when a named hurricane triggers it. We do not adjust claims; we document and scope the damage so the adjuster sees what the storm did, and we tell you which of the three buckets each item belongs in before you file.
Building Department in Holbrook
Holbrook straddles the Brookhaven and Islip town line and both are possible, so the department is confirmed by address before anything is filed. Emergency repairs to make the house safe and dry do not wait for a permit. The permanent repair that follows — structural work, re-roofing, electrical — is permitted work like any other, and we file it once the scope is agreed.
Free walkthrough in Holbrook. Call or text (631) 312-7441.
By the job in Holbrook: Tree Removal · Flood Cleanup · Storm Debris · Storm Roof & Siding
Frequently Asked Questions
Holbrook is in two towns — which building department handles my storm repair?
It depends on the address. Part of Holbrook files with the Town of Islip and part with the Town of Brookhaven, and the two do not have the same process or the same forms. Emergency repairs to make the house safe do not wait for either. For the permanent rebuild we identify the town from the tax map before we file, because a permit filed with the wrong town costs a week or two of the schedule.
How long before mould starts?
Mould can begin on wet building material within a day or two, which is why the wet material comes out and the drying starts immediately rather than after the adjuster's visit. Emergency mitigation is expected under the policy; photographs of what was removed protect the claim. Drying is done with equipment and measured with meters, not judged by touch.
What should I do first after storm damage?
Stay away from anything that could still fail — a tree on the roof, a sagging ceiling, a downed line, water near electrical — and call the utility for lines and gas. Photograph everything as it is before anyone moves a branch or pulls a carpet. Then call us. We tarp and board the same day where we can reach you, and the photographs are what your claim rests on.
Does homeowners insurance cover flooding from a hurricane?
Generally not. Water that rose from the bay, a canal, a creek or the ground is flood damage, covered by a separate flood policy — National Flood Insurance Program or private — and excluded from the homeowners policy. Rain that came in through wind damage to the roof or siding is a homeowners claim. Many bay-front houses have both after a hurricane, and we scope the two separately.
Related Guides
- Hurricane & Storm Damage Repair in Bay Shore, NY
- Hurricane & Storm Damage Repair in Islip, NY
- Hurricane & Storm Damage Repair — our service page
- Hurricane Damage Repair on Long Island
- What to Do in the First 48 Hours After Hurricane Damage
- Storm Damage Restoration in Holbrook — the insurance claim
Also Serving Holbrook
- ADUs in Holbrook — accessory apartments and grants
- Attic Insulation in Holbrook — air sealing, baffles and R-49 depth
- Basement Finishing in Holbrook — egress, ceiling height and moisture
- Bathroom Remodeling in Holbrook — full gut renovations
- Chimney Repair in Holbrook — repointing, crowns, caps and flashing
- Driveway Paving in Holbrook — blacktop, resurfacing and repairs
- Emergency Roof Repair in Holbrook — tarping, leaks and storm response
- Fallen Tree Removal & Roof Repair in Holbrook — tree off the house, roof supported and repaired
- Flood & Water Damage Cleanup in Holbrook — wet material out, drying metered
- Garage Conversion in Holbrook — turning the garage into living space
- Gutter Installation in Holbrook — seamless gutters, fascia and drainage
- House Painters in Holbrook — exteriors while the fall window holds
- Storm Damage & Insurance Restoration in Holbrook — emergency tarping and the claim
- Interior Painting in Holbrook — the right work for the cold months
- Kitchen Remodeling in Holbrook — cabinets, counters and layout
- Masonry & Pavers in Holbrook — patios, walkways and retaining walls
- Roofing in Holbrook — tear-offs, repairs and storm damage
- Siding in Holbrook — James Hardie, vinyl and cedar
- Storm Debris Removal & Cleanup in Holbrook — trees, building debris and hauling
- Storm Roof & Siding Repair in Holbrook — wind damage, tarped and rebuilt
- Windows & Doors in Holbrook — insert and full-frame replacement
Work With Alec's Construction
This guide is written by the crew that does the work. See Alec's Hurricane & Storm Damage Repair service — fallen trees, flooding, roof and siding damage, cleanup and the rebuild. One crew start to finish, free walkthrough and a written estimate inside 48 hours.
Booking the cold months now: we also handle Roofing and Storm Damage & Insurance Restoration.
Get a Free Estimate from Alec's Construction
Working across Suffolk County since 2018, one crew from start to finish. We come out, look at the actual job, and put a written number in your hand — no pressure, no obligation.
Or call (631) 312-7441