Water inside a Coram house after a storm has a clock on it. Mould can start on wet sheetrock and insulation within a day or two, and a house that sits wet while it waits for an adjuster becomes a mould job on top of a storm job. Alec's Construction gets the wet material out, the drying equipment in and the moisture metered, then rebuilds to the agreed scope, working out of the yard on Barton Avenue in East Patchogue. If there is water in the house now, call rather than fill in the form.
What a Storm Does in Coram
Coram is inland, in the middle of Brookhaven with no tidal water in any direction, and a hurricane here is a tree event on the sandy, pine-and-oak ground the hamlet was cut out of. The 1960s–80s splits, ranches and hi-ranches along the side streets off Route 112 and Middle Country Road stand under pitch pines that have grown tall and thin in the sixty years since, and a sustained wind after a wet day takes them over whole — roots and all — onto the low roof of the garage wing, the deck, the car, and the service drop. The oaks shed limbs instead of falling. What is left after the trees is wind damage to the low-slope roofs and gable ends that every split in central Suffolk shares, and rain driven in where the shingles lifted.
Rain Through the Roof, Water in the Basement
There is no tidal water here, so the water in a house after a storm came down — through the roof a tree opened, around a window the wind broke — or up through a basement that the sump could not keep ahead of when the power went out. Both are fresh water; the first is a homeowners claim and the second usually is not unless the policy carries a sump endorsement.
Two Kinds of Water, Two Claims
Water that came down — through a roof the wind opened, around a window it broke, behind siding it peeled — is wind-driven rain and a homeowners claim. Water that came up — from the bay, a canal, a creek, the ground — is flood, excluded from the homeowners policy and covered only by a separate flood policy. Most storm-damaged houses have some of both, and the two have to be documented separately from the first visit or the claims fight each other. We keep them separate on the scope.
What Comes Out
Wet carpet and pad. Insulation that took water, all of it. Sheetrock cut back above the water line to the next joint. Laminate and engineered floors that swelled. Cabinet boxes that sat in water. Soaked contents that cannot be cleaned. Everything photographed in place, photographed as it comes out, and kept where the adjuster can see it. Emergency mitigation is expected of you under the policy; it does not wait for the adjuster.
Drying Is Measured, Not Guessed
Commercial dehumidifiers and air movers, moisture readings on the framing every day, and nothing closed up until the numbers say dry. Where the water was salt — surge from the bay or a canal — the rules change: electrical that went under is replaced, not dried, and the framing gets washed down before it is dried, because salt keeps pulling moisture out of the air for years.
The Rebuild
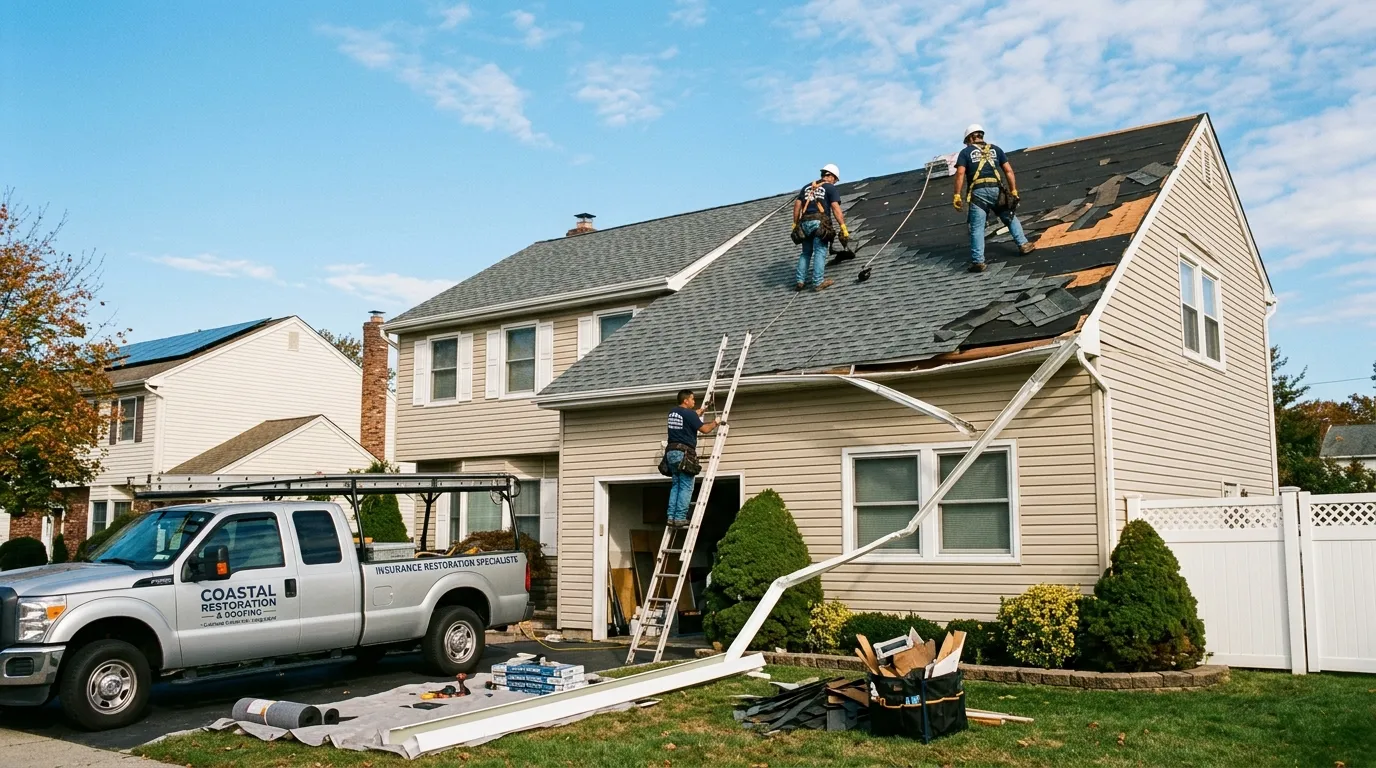
Insulation, sheetrock, trim, floors, cabinets, paint, and the electrical or mechanical that had to be replaced, on one scope with the cleanup. Where the water came in through the roof or the siding, the cause is fixed first so the new work does not get wet again.
Building Department in Coram
Coram files with the Town of Brookhaven. Emergency work to make the house safe and dry does not wait for a permit; the permanent repair is filed once the scope is agreed.
Free walkthrough in Coram. Call or text (631) 312-7441. Tell us whether the roof is open, whether a tree is on the structure and whether there is water inside, and we bring the right equipment on the first trip.
Frequently Asked Questions
A tree is leaning on my Coram house but has not gone through the roof. Is it an emergency?
Treat it as one. A tree resting on a roof is a load the roof was not framed for, it moves in every gust, and the damage it does grows while it sits there. We look at what it is resting on, decide whether the structure needs shoring before the tree comes off, and coordinate the removal so the weight comes off in the right order. Photograph it from the ground first, before anyone touches it — that is the claim.
Is the flooding covered by my homeowners policy?
Water that rose from the bay, a canal, a creek or the ground is flood damage, and a standard homeowners policy excludes it; it is covered only by a separate flood policy. Rain that came in through wind damage to the roof or siding is a homeowners claim. Where a house has both, they are documented separately from the first visit.
Can you pump out my basement today?
Where we can reach you, yes, once the water outside has gone down. Pumping a basement while the ground around it is still saturated can push the walls in. After that the wet material comes out and the drying starts the same visit.
Can wet drywall be dried instead of replaced?
Sometimes, if it was clean water, it was wet briefly and it has not lost its strength. Storm water is rarely clean, the insulation behind it holds water far longer than the board, and salt water is never dried. In practice sheetrock below the water line comes out, the insulation behind it comes out, and the framing is dried and metered before the wall is closed.
Related Guides
- Fallen Tree Removal & Roof Repair in Coram, NY
- Storm Debris Removal & Cleanup in Coram, NY
- Storm Roof & Siding Repair in Coram, NY
- Flood & Water Damage Cleanup in Patchogue, NY
- Flood & Water Damage Cleanup in Medford, NY
- Emergency Roof Repair & Tarping in Coram
- Hurricane & Storm Damage Repair in Coram, NY
- Storm Damage & Insurance Restoration in Coram
- Hurricane & Storm Damage Repair — our service page
Also Serving Coram
- ADUs in Coram — accessory apartments and grants
- Attic Insulation in Coram — air sealing, baffles and R-49 depth
- Basement Finishing in Coram — egress, ceiling height and moisture
- Bathroom Remodeling in Coram — full gut renovations
- Chimney Repair in Coram — repointing, crowns, caps and flashing
- Driveway Paving in Coram — blacktop, resurfacing and repairs
- Emergency Roof Repair in Coram — tarping, leaks and storm response
- Fallen Tree Removal & Roof Repair in Coram — tree off the house, roof supported and repaired
- Garage Conversion in Coram — turning the garage into living space
- Gutter Installation in Coram — seamless gutters, fascia and drainage
- House Painters in Coram — exteriors while the fall window holds
- Hurricane & Storm Damage Repair in Coram — trees, flooding, cleanup and repairs
- Storm Damage & Insurance Restoration in Coram — emergency tarping and the claim
- Interior Painting in Coram — the right work for the cold months
- Kitchen Remodeling in Coram — cabinets, counters and layout
- Masonry & Pavers in Coram — patios, walkways and retaining walls
- Roofing in Coram — tear-offs, repairs and storm damage
- Siding in Coram — James Hardie, vinyl and cedar
- Storm Debris Removal & Cleanup in Coram — trees, building debris and hauling
- Storm Roof & Siding Repair in Coram — wind damage, tarped and rebuilt
- Windows & Doors in Coram — insert and full-frame replacement
Work With Alec's Construction
This guide is written by the crew that does the work. See Alec's Hurricane & Storm Damage Repair service — fallen trees, flooding, roof and siding damage, cleanup and the rebuild. Licensed and insured on Long Island, one crew start to finish, free walkthrough and a written estimate inside 48 hours.
Booking the cold months now: we also handle Roofing and Storm Damage & Insurance Restoration.
Get a Free Estimate from Alec's Construction
Licensed and insured, working across Nassau and Suffolk County since 2018. We come out, look at the actual job, and put a written number in your hand — no pressure, no obligation.
Or call (631) 312-7441